Leverage trading in crypto means taking market exposure larger than the capital supporting the position. It can increase the gain or loss relative to that capital, while introducing margin requirements and the possibility of forced liquidation. A leverage setting is not a risk limit.
The essential distinction is between position size, which drives the dollar effect of a price move, and collateral, which supports that position. Understanding both is more useful than choosing the largest multiplier an exchange displays.
What leverage actually changes
For a simple position, initial exposure divided by allocated collateral gives an opening leverage ratio. A hypothetical $2,000 position supported by $500 represents 4× leverage. This is a teaching example, not a recommended trade or a quoted platform requirement.
Two products can provide leveraged exposure in different ways:
- Spot margin: the trader uses a margin extension or borrowing arrangement to buy or sell assets, with repayment and collateral obligations.
- Derivatives: the trader holds a contract whose value depends on an underlying asset. Opening a futures or perpetual position does not mean buying the underlying coins for withdrawal.
Contract design matters. The calculations below concern a simple linear position with profit and loss measured in dollars. Inverse contracts, options and more complex portfolios require different calculations. Product availability and eligibility also depend on the provider and jurisdiction.
A worked example: exposure versus collateral
Suppose a hypothetical asset costs $100. A long position of 20 units has a $2,000 entry value. It is supported by $500 of collateral, and we initially ignore all fees and funding.
Long-position gross profit or loss = units × (exit price − entry price)
| Hypothetical exit price | Asset price change | Gross profit or loss | Result relative to $500 collateral |
|---|---|---|---|
| $102 | +2% | +$40 | +8% |
| $100 | 0% | $0 | 0% |
| $98 | −2% | −$40 | −8% |
| $95 | −5% | −$100 | −20% |
These are arithmetic scenarios, not forecasts. The collateral return is larger than the asset's percentage change because the position is four times the collateral. A short position reverses the direction of gross profit and loss for the same price changes.
Now keep the 20-unit position unchanged but support it with $1,000 instead. The loss on a move from $100 to $98 is still $40. It is 4% of that larger collateral amount. Changing a leverage selector does not independently multiply the dollar loss when the position quantity stays the same.
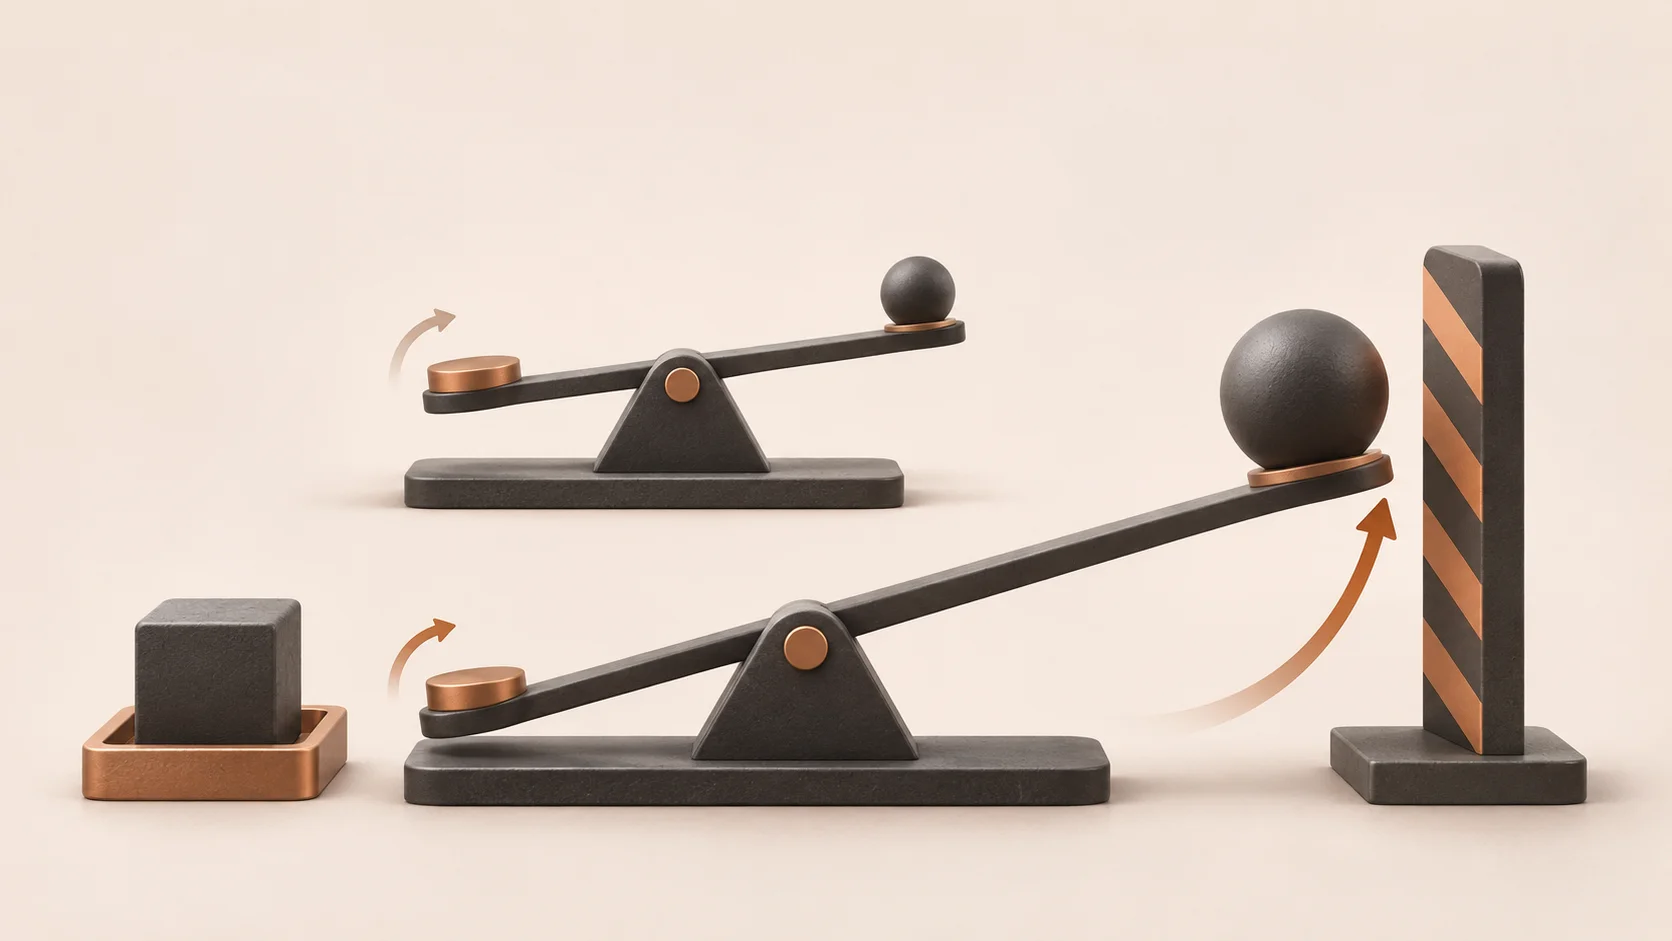
Conceptual illustration of a small collateral base supporting larger market exposure; not market data or a liquidation-price chart.
Initial margin and maintenance margin serve different purposes
Initial margin is the collateral requirement for opening a position. Maintenance margin is the requirement for keeping exposure open. Requirements can depend on the contract, position size and account rules.
Account equity changes with unrealized profit or loss and charges. If the relevant equity falls below the maintenance requirement, the platform can begin liquidation: reducing or closing positions according to its rules. This can happen before every dollar of collateral has been lost. Some systems use partial liquidation first.
The shortcut “10× leverage means liquidation after exactly a 10% move” is therefore unreliable. It ignores maintenance requirements, costs, additional collateral, other positions and the price used for the calculation.
The displayed market price may not be the liquidation reference
Many derivatives systems use a mark price for margin checks. That reference can differ from the last traded price displayed on a chart. Kraken's derivatives documentation, for example, describes its estimated liquidation price in terms of mark price and account equity.
Treat a displayed liquidation price as an estimate tied to the current account state. Fees, funding and changes elsewhere in the account can alter the margin buffer. Do not assume that a warning or grace period will arrive before forced closure.
Cross margin and isolated margin
| Margin arrangement | How collateral is generally assigned | Question to resolve before entry |
|---|---|---|
| Isolated margin | A designated amount supports an individual position | Can automatic additions draw more money into the position? |
| Cross margin | Eligible collateral supports positions within a shared margin account | Which balances and other positions share the risk? |
Cross margin can allow a loss in one position to consume collateral that also supports another. Isolated margin separates the allocation, but it does not make a bad trade safe. Check whether automatic margin additions are enabled and how the provider treats fees, deficits and collateral transfers.
On some multi-collateral accounts, a fall in collateral value can still expose isolated positions to account-wide liquidation; check the product's rules.
Do not assume that the opening margin is a universal maximum loss. Some products provide specific balance protections; others can leave a deficit after liquidation. The relevant account agreement determines the obligations.
Fees and funding apply to more than the deposit
Trading fees commonly depend on executed notional value. To illustrate, assume a hypothetical 0.05% fee on each side of the $2,000 position above. Entry costs $1. If it closes at the same price, exit costs another $1. The $2 total is 0.10% of position value but 0.40% of the $500 collateral.
The fee rate is invented solely for this calculation. Actual rates and the exit notional may differ. Spread and slippage add further execution costs.
Spot margin may carry opening, borrowing or rollover charges. Perpetual contracts can involve funding payments between long and short positions; the direction and amount can change. Funding is distinct from the trading fee, and payment schedules vary. Neither holding a position longer nor increasing leverage makes these charges disappear.
Why a stop order is not a guaranteed loss ceiling
A stop-market order activates a market order when its trigger condition is met. The eventual fill can be worse than the trigger price. A stop-limit order adds a price restriction but can remain unfilled. In a fast market, either limitation matters.
Check the stop's trigger reference, quantity and reduce-only behavior where supported. A separate stop left open after another exit may create an unintended order. Also compare the intended exit with the liquidation rules: a stop placed beyond the liquidation threshold cannot be relied on to close the trade first.
Questions to answer before using leverage
Write down the position quantity, entry value, supporting collateral and estimated loss at the intended exit. Then identify the maintenance requirement, margin mode, funding or borrowing charges, and what happens if the exit fills badly.
A crypto paper-trading exercise can help you practice recording position size and costs without risking funds. A basic spot ledger does not reproduce derivatives liquidation, so any margin simulation also needs the specific contract rules.
If those details are unclear, a multiplier on the order ticket is not enough information to proceed. Our starting-capital guide explains position value and planned loss budgets using unleveraged examples. The same separation of quantities is useful when reviewing more complex products.
Educational examples only; no trading outcome is guaranteed. Technical sources checked November 21, 2026.